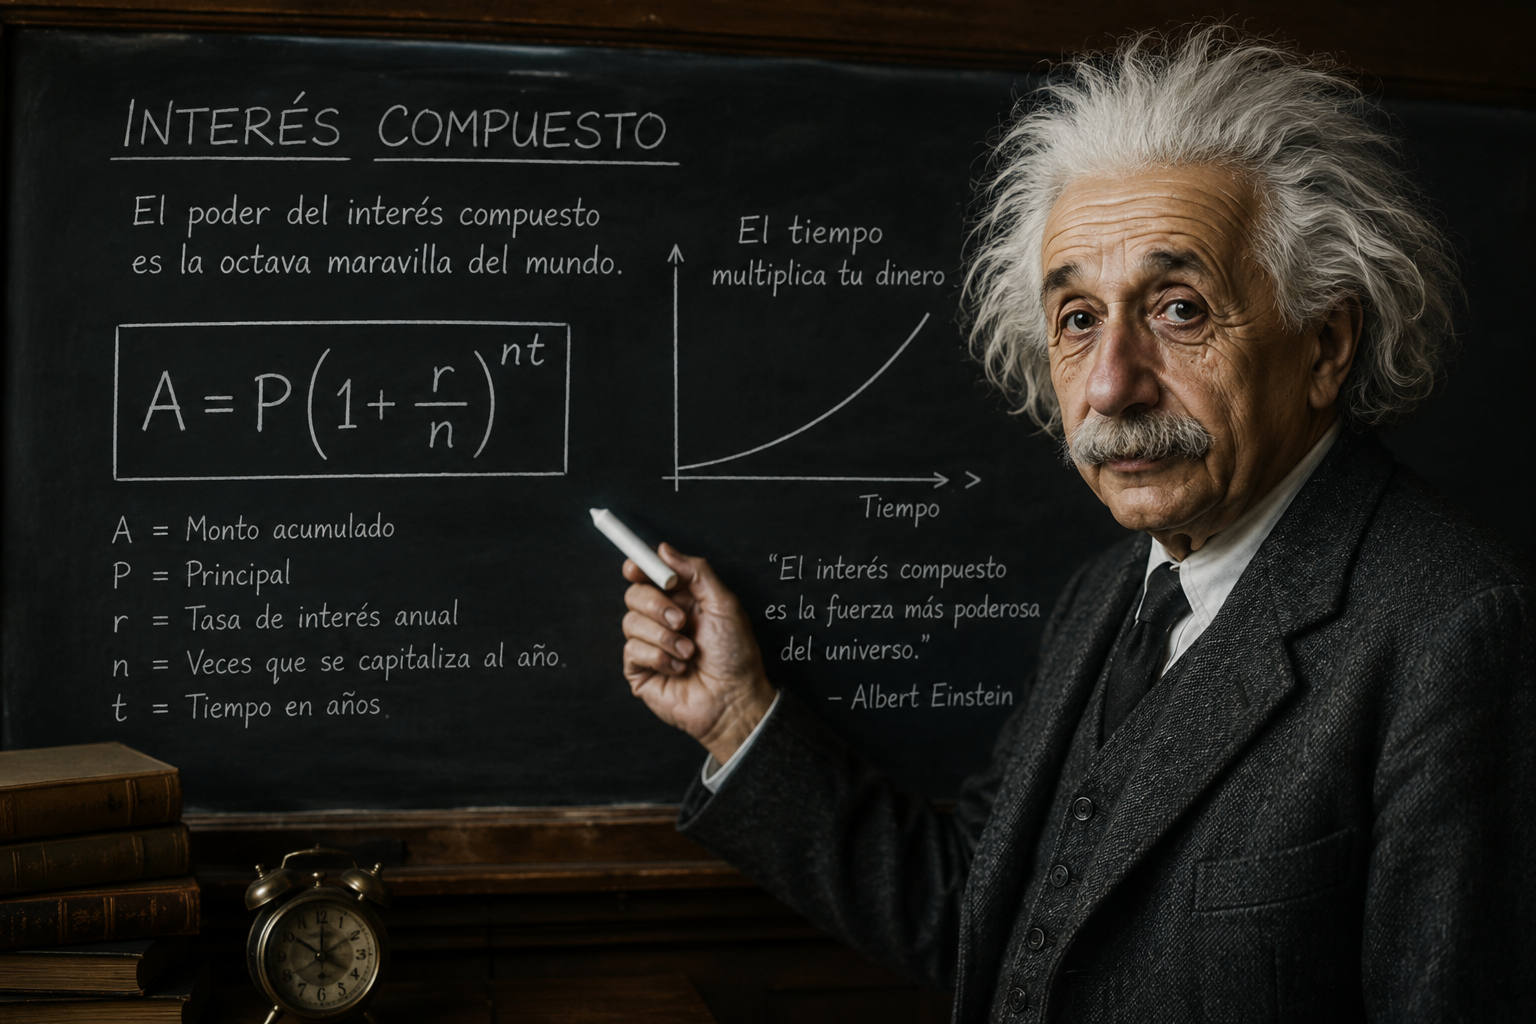
Compound interest
"Compound interest is the eighth wonder of the world. He who understands it, earns it; he who doesn't, pays it" physicist Albert Einstein once stated. In practical terms, this tool consists of continuously reinvesting the returns generated by an initial investment. As earnings are added to the original capital, subsequent interest is calculated on an ever-increasing amount, causing a snowball effect.
When it works in our favor, capital grows geometrically. For example: if you invest $1,000 with a 10% annual return, at the end of the first year you will have $1,100. If you keep that money invested and achieve another 10% the second year, your gain will not be calculated on the initial $1,000, but on the accumulated $1,100. Thus, year two will close with $1,210 instead of $1,200. After 5 years, that $1,000 will have transformed into $1,611, accelerating the growth rate with each passing year.
Its Inverse Effect: The Debt Trap
Used against you, compound interest is financially lethal. This is the mechanism banking institutions apply to credit cards or revolving loans: interest not cleared on time is capitalized (added to the outstanding balance), causing the total debt to grow uncontrollably as the payment term extends.
The Four Pillars of the Formula
To master compound interest, it is essential to understand the four variables that dictate its behavior:
Initial Capital: The money you start with. Although a larger capital accelerates the process, it is not the most determining factor in the long run.
Periodic Contributions: The system's fuel. Adding money monthly or annually drastically shortens the time needed to reach your financial goals, as it injects fresh capital that also begins to generate its own interest.
Interest Rate (Return): The profit percentage. A difference of just 2% per year can double or triple the accumulated wealth after a few decades.
Time (Term): The most critical factor. Compound interest is directly proportional to patience; the most spectacular results are always concentrated in the final years.
The Real Leap: Periodic Contributions
The benefit of this formula multiplies exponentially if we combine automatic reinvestment with constant capital contributions (systematic saving). Understanding this dynamic and executing it with discipline is the ultimate key to financial progress.
Practical Case: A Child's Freedom Fund
Imagine that when your child is born, you decide to open an investment account in their name with an initial capital of €5,000. Subsequently, you add annual contributions of €1,000 (which equates to less than €84 a month, or barely €2.70 a day). If that money is placed in an index vehicle or managed by a professional who achieves an average annual return rate of 13%, and it remains untouched until your child turns 30, the accumulated capital will reach €526,895.
Even though the real value must be adjusted in the future based on the impact of inflation, the result remains extraordinary. This demonstrates how a modest foundation, backed by consistency, generates real wealth over the long term.
Investor Psychology: The Invisible Phase
The greatest enemy of compound interest is not the markets, but impatience. During the first years of an investment, growth appears linear and almost imperceptible. This is what experts call the "plateau of latent potential" (or the plateau of disappointment): you work, save, and reinvest, but the numbers barely move.
However, if discipline is maintained long enough, the investment curve crosses an inflection point where growth becomes vertical. The key to financial success is not being a financial genius, but having the temperance not to interrupt the process when it seems like "nothing is happening."
Conclusion: The Time Factor and the Silent Enemy
When planning for the long term, we must always take into account inflation, which is the rising cost of living. If average inflation is 3%, the €526,895 from your child's example will not have the same purchasing power as today, but it will still represent a considerable fortune that will guarantee their stability. The best way to beat inflation is, precisely, by investing at rates higher than it.
You do not need your parents to have opened that account for you; you can start this process today with small amounts. Returns and time are the two master variables of your finances. To maximize the former, we look for strategies and assets that pursue solid returns; to activate the latter, there is only one way: start today.
Simulate Your Own Numbers
In this link, you can project different financial scenarios by modifying the basic variables: initial capital (principal), annual contributions (addition), years of investment (years to grow), and the estimated return rate (interest rate).